Last Updated: October 22, 2026
Utah real estate investors are not wanting for opportunities in Salt Lake City and across the Wasatch Front. However, long-term success rests on a few key strategies, one of them being structuring debt around realistic valuation metrics. Whether it is a multi-family property or an underperforming industrial site, securing acquisition capital requires a firm grasp of how private lenders analyze deal structures.
The private lenders I’m referring to here are essentially Utah’s hard money firms. One of the leading firms in the state is Salt Lake City’s Actium Lending (actiumlending.com/hard-money-loans). Actium and its competitors work alongside real estate investors to finance acquisitions of some of the most competitive properties in the state.
The big difference between Utah hard money lenders and their conventional counterparts is loan basis. Conventional lenders base loans on things like debt-to-income ratios and income statements. But a hard money lender in Salt Lake City bases its decision on asset value and purchase economics.
Table of Contents
Loan-to-Value (LTV) on Purchase Price
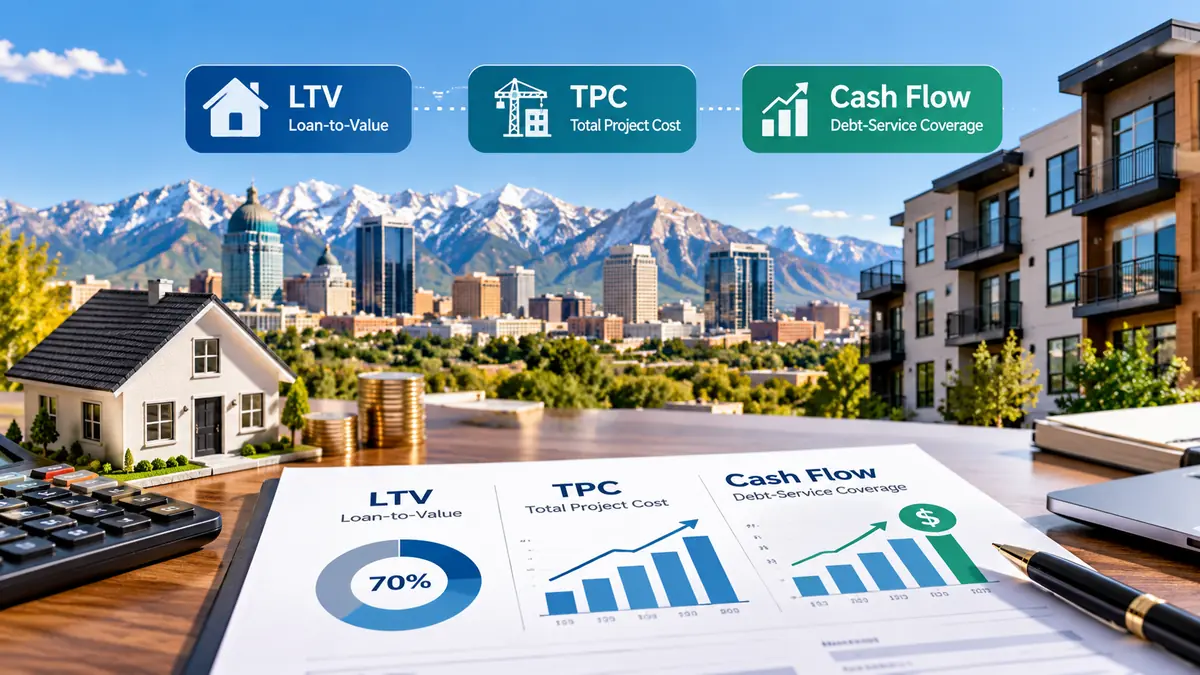
Although hard money and conventional lenders operate on fundamentally different business models, they do share some things in common. At the top of the list is the loan-to-value (LTV) ratio. LTV measures the percentage of the purchase price that will be covered by the loan. It is important to lenders because it serves as a primary risk indicator.
Because hard money firms operate as asset-based lenders, they need to prioritize equity protection. So a typical Utah hard money loan will carry a lower LTV compared to a bank’s offer. I cannot provide any hard and fast numbers, but 65%-75% would not be abnormal.
Despite comparatively low LTVs, hard money offers advantages investors appreciate:
- Limited Personal Liability – Hard money loans are backed by the assets being financed. As a result, a buy-and-hold investor’s personal liability is limited.
- Liquidity Preservation – Hard money loans are usually structured as interest-only loans. The lower monthly payments such arrangements afford give investors more cash to put into property stabilization.
- Rapid Execution – Because hard money loans are asset-based, underwriting can be completed much more quickly. Lenders can usually get from loan approval to full funding in a week or less.
Lower LTVs can be challenging for investors without enough liquidity to make a significant down payment. In addition, hard money loans do carry higher interest rates. But given what hard money brings to the table, experienced investors are willing to overlook what are generally considered slight disadvantages.
Total Project Cost
Next up, buy-and-hold investors need to evaluate value-add acquisitions against total project cost (TPC). Hard money lenders certainly do. TPC includes purchase price, the capital expenditure budget, and all closing and holding costs.
Hard money lenders look at TPC and compare it to the amount of money being requested. The ratio they come up with is known as the loan-to-cost (LTC) ratio. Lenders set an LTC they feel is appropriate for forcing the borrower to maintain sufficient skin in the game. At the same time, they know a borrower needs to preserve enough capital to stabilize a property in preparation for loan exit.
Debt-Service Coverage and Cash Flow
Finally, even though hard money lending is asset-based, most lenders will take a good look at a property’s debt-service coverage and future cash flow potential. The idea is to analyze whether the acquisition represents a wise investment. They do not want to end up as landlords if the acquisition goes south. So these two metrics matter.
Utah hard money lenders evaluate LTV and cost metrics before financing value-add buy-and-hold properties. Smart investors do the same thing before they even think about applying for a loan.